Loading, please wait...
Loading, please wait...

Problematic gambling creates devastating financial consequences that frequently ripple across families and communities. Recent clinical and epidemiological investigations reveal that gambling-related debt represents one of the most severe manifestations of behavioral addiction. When individuals exhaust their liquid assets, they often borrow money to chase losses or sustain gambling behaviors. Consequently, debt accumulation accelerates psychological distress, exacerbating depressive symptoms and suicidal ideation. A nationwide investigation among Finnish helpline callers evaluated individuals who utilized borrowed funds to finance their wagering. The researchers examined over 4,200 help-seekers between 2019 and 2022. Strikingly, nearly 40 percent of these individuals reported gambling with debt money. In addition, the prevalence of borrowing peaked in 2019 before declining in subsequent years, particularly after 2020. This trajectory suggests that broader economic shocks and public regulatory measures substantially influence gambling expenditure. Furthermore, clinicians must recognize that financial insolvency acts as a distinct clinical driver. Traditional addiction screening tools often fail to capture borrowing severity until severe legal or economic distress occurs. Therefore, primary care physicians and psychiatrists must evaluate debt exposure during initial psychiatric evaluations to identify acute psychosocial vulnerability early.
Epidemiological data indicate that gambling-related liabilities do not distribute equally across the general population. Specifically, the study highlighted that individuals aged 35 to 54 years exhibited the highest likelihood of accumulating debt from gambling activities. In contrast to common assumptions that young, unemployed adults face the greatest financial jeopardy, employed individuals actively participating in the labor force demonstrated higher rates of borrowing. This discrepancy occurs because gainfully employed adults possess greater creditworthiness, enabling them to secure consumer credit, personal loans, and digital credit lines. Unfortunately, predatory lending services actively target working adults with high-interest financial products. Because these individuals maintain steady incomes, they often conceal their spiraling financial deficits from spouses, employers, and healthcare providers for extended periods. As debt compounds, psychological shame and stigma prevent timely help-seeking. Moreover, cultural pressures and breadwinner expectations in many societies, including India, aggravate this emotional burden. When financial mechanisms collapse, patients experience sudden crises marked by acute panic, family disintegration, and occupational disruption. Medical professionals must understand that economic productivity does not protect against compulsive financial self-harm. Instead, accessible credit often accelerates the path toward profound insolvency.
The nature of the gambling product strongly determines the likelihood of severe indebtedness. In the Finnish cohort, researchers identified online gambling and poker as potent drivers of borrowing behavior. Digital platforms offer continuous availability, immediate payment integration, and complete social detachment. Consequently, gamblers lose perception of physical currency, making reckless wagers far more probable. Furthermore, digital poker involves complex psychological elements, including the illusion of skill and protracted session durations. Players frequently convince themselves that sustained play will eventually recoup losses, leading to continuous re-buys funded by credit cards or instant loans. In India, a parallel phenomenon occurs with the explosive growth of online rummy, poker, and sports betting applications. Digital payment systems, such as unified payments interfaces, enable instantaneous fund transfers with minimal cognitive friction. Thus, users can access digital credit or microloans in seconds without leaving the gaming platform. While land-based gambling venues offer natural pauses and physical cash constraints, internet platforms remove all protective friction. Therefore, physicians treating individuals with digital gaming habits must specifically evaluate whether patients utilize borrowing to sustain their internet play.
Routine clinical consultations rarely explore detailed financial behaviors, leaving significant behavioral addiction undetected until catastrophe strikes. However, incorporating structured financial screening into psychiatric evaluations can unveil hidden illness early. Clinicians should specifically inquire about loan applications, borrowing from relatives, and unpaid credit card balances. Because patients with gambling disorder experience intense humiliation, direct questioning must occur within an empathetic, non-judgmental environment. For example, clinicians can ask whether financial pressures have increased or if the patient has sought loans to cover unexpected recreational expenses. Furthermore, healthcare providers must differentiate gambling disorder from primary affective disorders. While manic episodes in bipolar disorder can trigger reckless spending, chronic debt accumulation typically reflects persistent gambling pathology. In addition, adult attention-deficit/hyperactivity disorder often co-occurs with gambling disorder, where high impulsivity accelerates hazardous financial choices. Comprehensive screening instruments, such as the Problem Gambling Severity Index, provide valuable objective scoring. Nevertheless, clinicians must pair standardized psychometric tools with targeted inquiries into debt status. Identifying borrowed capital early allows physicians to coordinate timely psychosocial care before legal consequences or bankruptcy devastate the patient’s livelihood.
Managing debt-financed gambling requires integrated medical, psychotherapeutic, and socio-legal strategies. Cognitive behavioral therapy remains the primary evidence-based modality for modifying cognitive distortions, such as the gambler's fallacy and loss-chasing beliefs. Through therapy, patients learn effective distress tolerance and emotional regulation skills. In addition, clinicians should consider pharmacological options, including naltrexone or selective serotonin reuptake inhibitors, when co-occurring psychiatric disorders or intense cravings persist. However, psychiatric intervention alone cannot resolve severe legal obligations or crushing debt burdens. Therefore, multidisciplinary teams must connect patients with certified financial counseling services and debt restructuring programs. Restricting direct access to personal credit cards and establishing third-party financial oversight often provide essential barriers against relapse. Beyond individual clinical care, public health measures play an indispensable protective role. The Finnish study demonstrated that regulatory shifts and economic factors meaningfully altered borrowing trends between 2019 and 2022. Consequently, governments must enforce statutory limits on instant loan approvals, cap extortionate interest rates, and mandate cooling-off periods on digital betting platforms. Combining targeted clinical treatment with robust financial consumer protection creates a vital safety net for vulnerable populations.
Gambling-related debt dramatically escalates suicide risk among psychiatric patients by triggering profound feelings of shame, hopelessness, and acute panic. When financial resources collapse and creditors demand repayment, individuals often perceive suicide as the only escape from overwhelming legal or domestic ruin. Therefore, clinicians must routinely assess suicidal ideation whenever patients present with severe indebtedness, conducting urgent psychiatric evaluations and establishing protective crisis interventions immediately to safeguard patient safety.
Employed individuals possess documented income streams, verified bank records, and higher credit ratings, granting them seamless access to unsecured loans, credit cards, and digital lending applications. Conversely, unemployed persons face strict underwriting barriers that limit credit availability. Consequently, employed individuals can borrow substantial sums rapidly to chase gambling losses. This dynamic enables working adults to conceal catastrophic behavioral addiction behind regular paychecks until debts compound into severe financial insolvency.
Although health authorities have not approved medications specifically for gambling disorder, several pharmacotherapies demonstrate meaningful clinical efficacy in trials. Opioid antagonists, such as naltrexone, effectively reduce gambling urges by modulating central dopamine reward pathways. Additionally, selective serotonin reuptake inhibitors help manage comorbid anxiety, impulsive tendencies, and depressive symptoms. Psychiatrists frequently prescribe mood stabilizers or second-generation antipsychotics when patients exhibit profound behavioral dysregulation, always combining pharmacotherapy with intensive cognitive behavioral therapy for optimal recovery outcomes.
Disclaimer: This content is for informational and educational purposes only... Refer to the latest local and national guidelines for clinical practice.
References
Marionneau V et al. Gambling consumption and socio-demographic characteristics among help-seekers with gambling-related debt. Scand J Public Health. 2026 Oct 08. doi: 10.1177/14034948261488598. PMID: 42845140.
Wardle H, Degenhardt L, Marionneau V, et al. The Lancet Public Health Commission on gambling. Lancet Public Health. 2024;9(12):e950-e994.
Abbott MW. The epidemiology of gambling disorder and concurrent disorders. In: Bowden-Jones H, Prever F, eds. Gambling Disorders in Clinical Practice. Routledge; 2019.
Read summarized clinical updates, watch expert medical content, and earn CME certifications right from your smartphone.
Open your smartphone camera to scan and install.


A nationwide study reveals that 39% of gambling help-seekers incur gambling-related debt, with highest rates among employed individuals aged 35 to 54. Online gambling and poker drive substantial borrowing, requiring targeted psychiatric screening, addiction treatment, and stronger consumer credit protections.
Today
Hospitalization for severe viral lower respiratory tract disease causes lasting physical, psychological, and productivity burdens for patients and their caregivers. Real-world multinational data reveal major gaps in discharge planning, emphasizing the urgent need for structured transitional pulmonary care.
Today
New evidence from Karolinska Institutet shows women vaccinated against HPV prior to conception have significantly lower rates of preterm birth and major perinatal complications. Clinicians in India can leverage these findings to strengthen adolescent immunisation and reproductive health advocacy.
Today
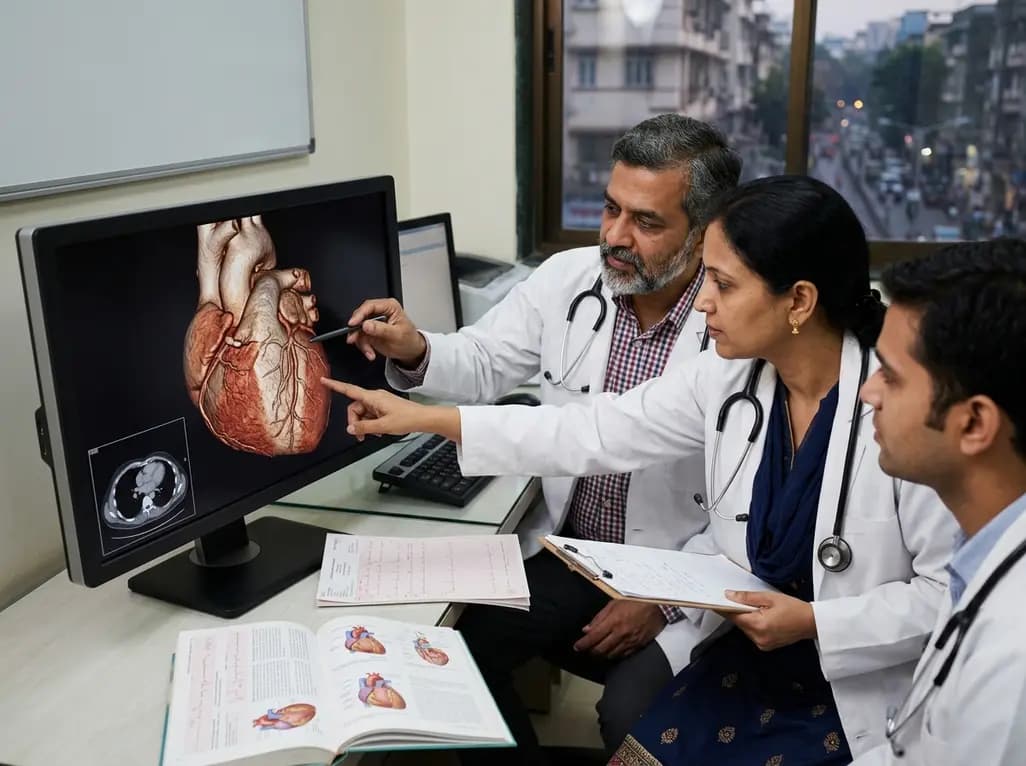
Cinematic rendering utilizes advanced global illumination to transform coronary CT angiography datasets. This imaging technique provides lifelike depth perception, helping cardiologists and surgeons precisely evaluate anomalous coronary artery origins, high-risk interarterial courses, and post-surgical anatomy.
Today
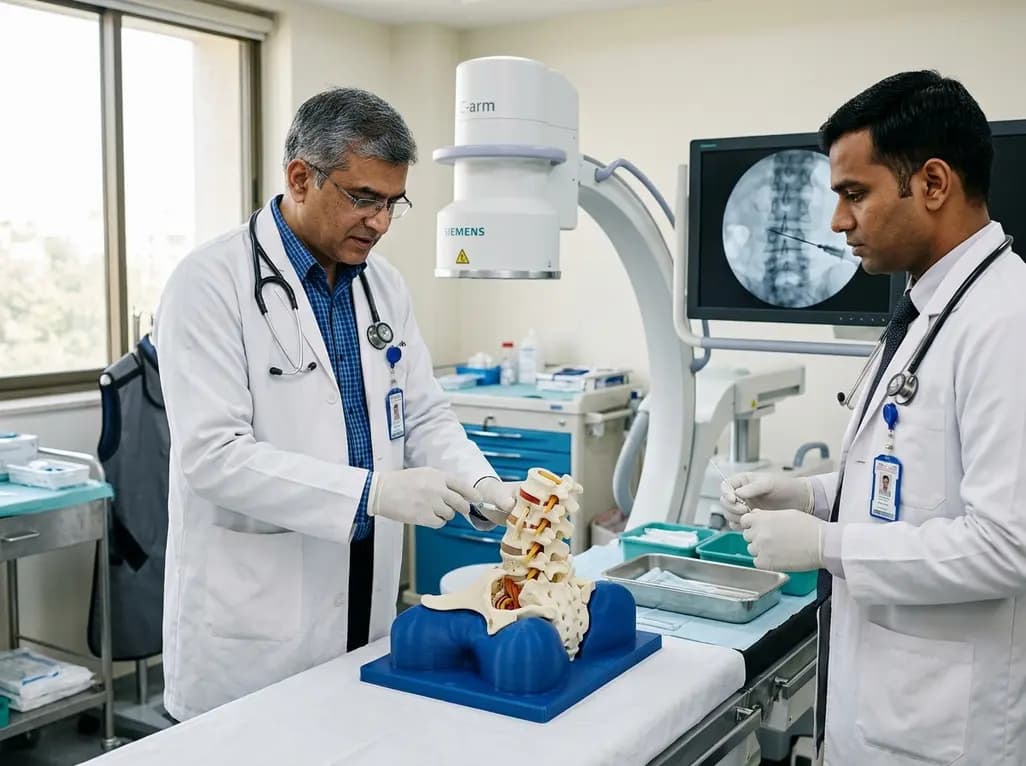
A novel 3D-printed lumbar spine simulator with tunable radiopacity provides realistic tactile and radiographic feedback for fluoroscopy-guided intervertebral disc puncture training, offering a low-cost, ethical alternative to cadaver models.
Today
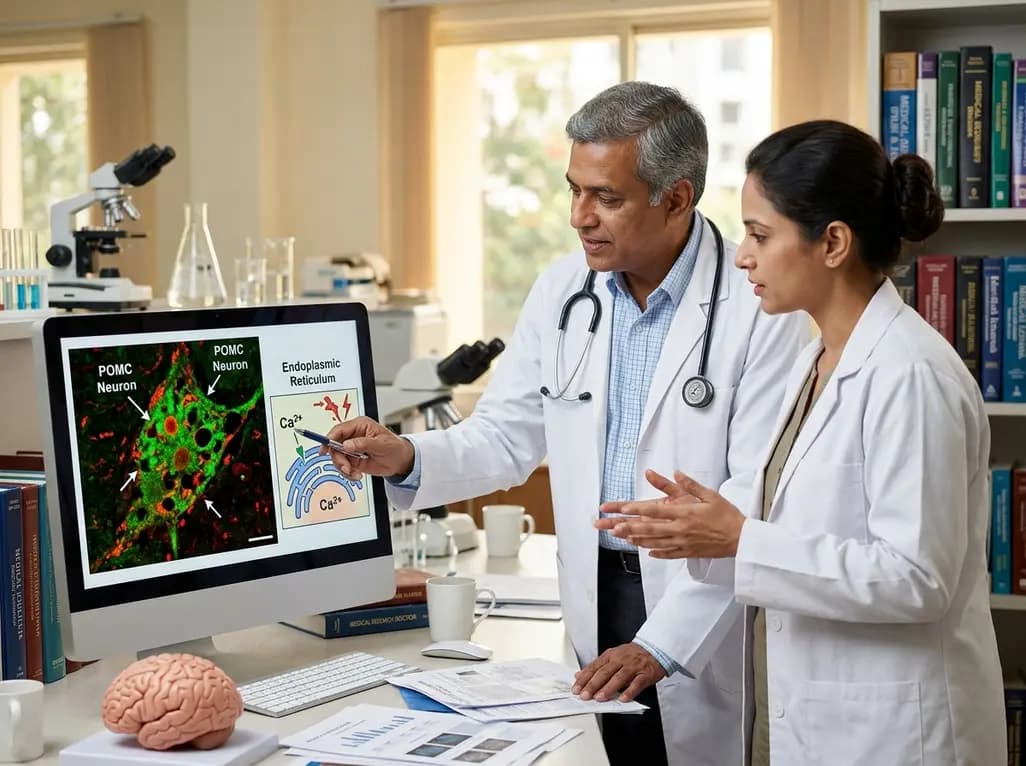
A breakthrough study reveals that loss of SELENOT in hypothalamic POMC neurons triggers premature cellular senescence, ATF6α stress activation, and ER calcium depletion, linking neuroendocrine decay to metabolic disease.
Today